
Blask’s latest iGaming market insights reveal shifting player demand across key markets, from a sharp decline in offshore betting searches in Turkey to the Philippines overtaking Brazil in global search demand.
The report also highlights record growth across Africa, the impact of Alberta’s regulated market launch, and Pragmatic Play’s strong visibility in casino games.
Blask: Turkey’s offshore iGaming demand drops by 2/3 after a 102-arrest illegal betting raid
Turkey’s Blask Index fell 68% in a single day on October 13, from 1.50 million to 483,000, the day the Interior Ministry announced the detention of 102 suspects in an illegal betting operation.
Demand for brands in Blask’s Offshore group fell by two-thirds on average over the following six days, while demand for brands in the Mixed group, which includes sports-betting names such as Nesine and Iddaa, rose.
Turkey’s Interior Ministry said on October 13 that the gendarmerie, working with the Financial Crimes Investigation Board (MASAK) and the Batman public prosecutor’s office, detained 102 suspects across 13 provinces. Authorities identified ₺8.5 billion ($171.5 million) in fund movements through accounts linked to illegal betting.
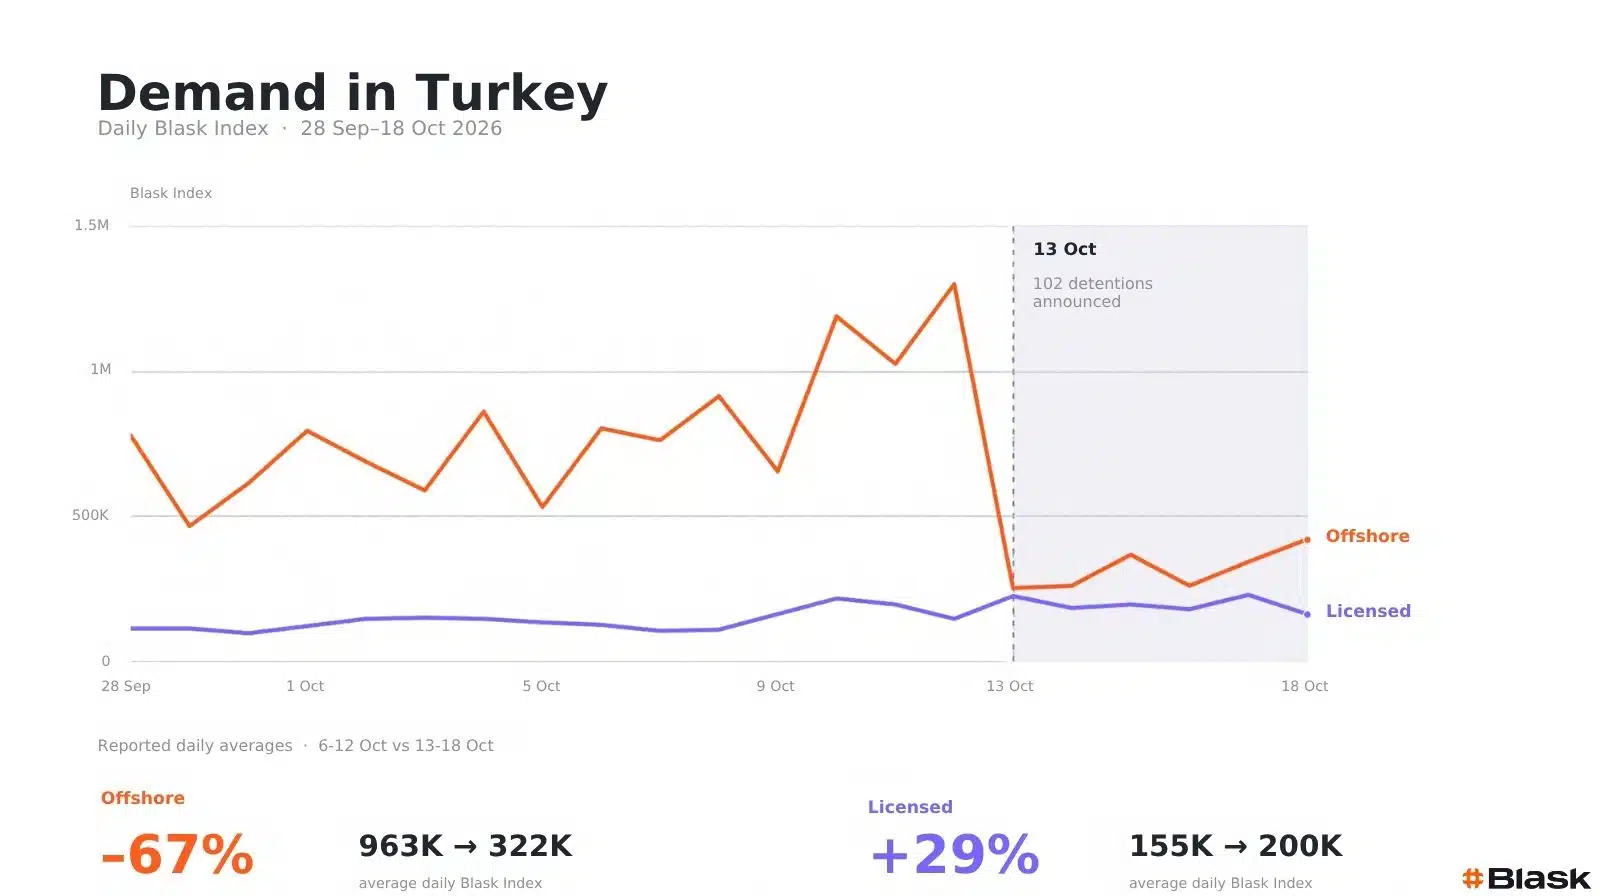
Blask’s daily data shows the break arriving on the announcement date, not before it. The index ran at 1.23 million to 1.50 million a day over October 10–12, then dropped to between 441,000 and 600,000 a day for October 13–18.
Brands in the Offshore group averaged roughly 963,000 a day in the seven days to October 12 and 322,000 a day over October 13–18, a fall of 67%. Brands in the Mixed group averaged 155,000 a day before and 200,000 after, an increase of 29%. The Mixed group’s share of the daily index rose from 10–16% on October 8–12 to 35–47% on October 13–17.
The comparison needs context.
The weekend before the announcement was unusually busy: the late-September to early-October median was about 729,000 a day, so the pre-announcement peak sat well above normal. Against that median, the October 13–18 average of about 522,000 a day is roughly 28% lower.
Early data for October 19 suggest the Offshore group’s share of demand is moving back toward its earlier level, so it remains to be seen whether the drop persists. The Süper Lig also played its eighth round during the window, which makes the football calendar a second factor alongside the raid.
Blask Index is a real-time measure of market demand volume for iGaming brands in a given country, based on normalized search data. It measures search attention, not betting handle or revenue, and it does not establish that the raid caused the change in search behaviour.
Philippines tops Blask Index after 87% annual growth in search demand
September’s search ranking put the Philippines ahead of Brazil, although the Brazilian market retained a substantial lead in projected revenue.
The Philippines became the largest market by iGaming search demand among countries tracked by Blask in September 2026. It finished ahead of Brazil and India, reversing the pattern seen throughout the first eight months of the year, when Brazilian demand consistently exceeded Philippine levels.
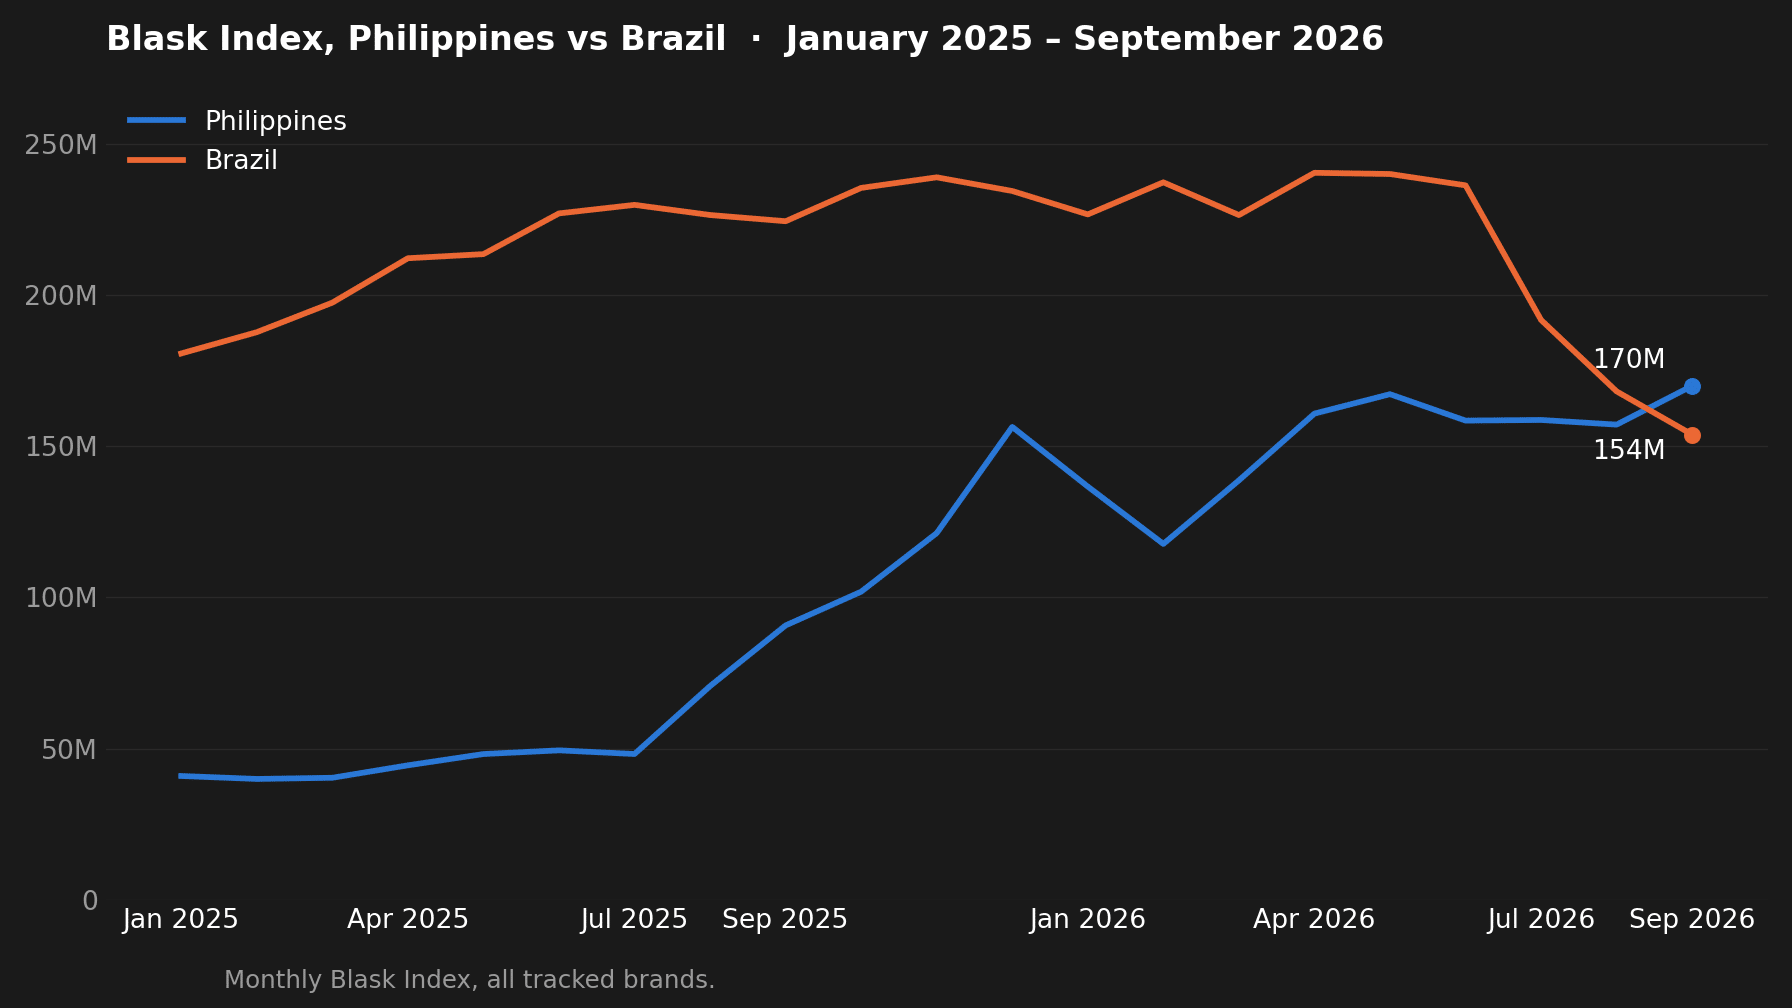
The change at the top does not extend to revenue estimates. Brazil’s September CEB, Blask’s projected revenue metric, was 53% higher than the Philippine figure. Licensed operators also accounted for a much larger proportion of the Brazilian total: 97%, compared with 62% in the Philippines. Higher search demand therefore did not translate into a higher revenue benchmark.
Philippine growth contrasts with Brazil’s decline
The Philippines gained ground on both monthly and annual comparisons. Its September Blask Index increased by 8% from August and by 87% from September 2025. Brazil recorded declines over both periods, falling 9% month on month and 31% year on year.
Three brands attracted more than half of Philippine search demand during September: PlayTime, Casino Plus and Bingo Plus. Their combined share shows how much of the country’s growing interest remained concentrated around a small group of operators.
Brazil’s contraction preceded the October shutdown
The ranking changed as restrictions began to reshape Brazil’s licensed betting sector. On 28 September, the Chamber of Deputies published Provisional Measure 1394/26, which stopped new deposits on licensed platforms.
September’s decline in Brazilian search demand came before authorized sites were taken offline. On 6 October, the justice ministry reported the first day without licensed betting platforms operating online.
The monthly figures thus capture the Philippines moving into first place during the opening stage of Brazil’s market closure, before the full effect of the October shutdown could appear in Blask Index.
Blask: African iGaming demand breaks record with 19% September jump
Growth across 40 markets pushed Blask Index above its previous December peak. The region’s projected revenue benchmark also reached a new high.
September 2026 set a new monthly record for iGaming search demand across the 42 African countries monitored by Blask. The combined Blask Index increased 19% from August, surpassing the previous high, recorded in December 2025, by 3%.
Tanzania, Nigeria and Mozambique contributed approximately 40% of the month’s increase. The expansion extended across almost the entire tracked region: Mali and Libya were the only countries to register declines.
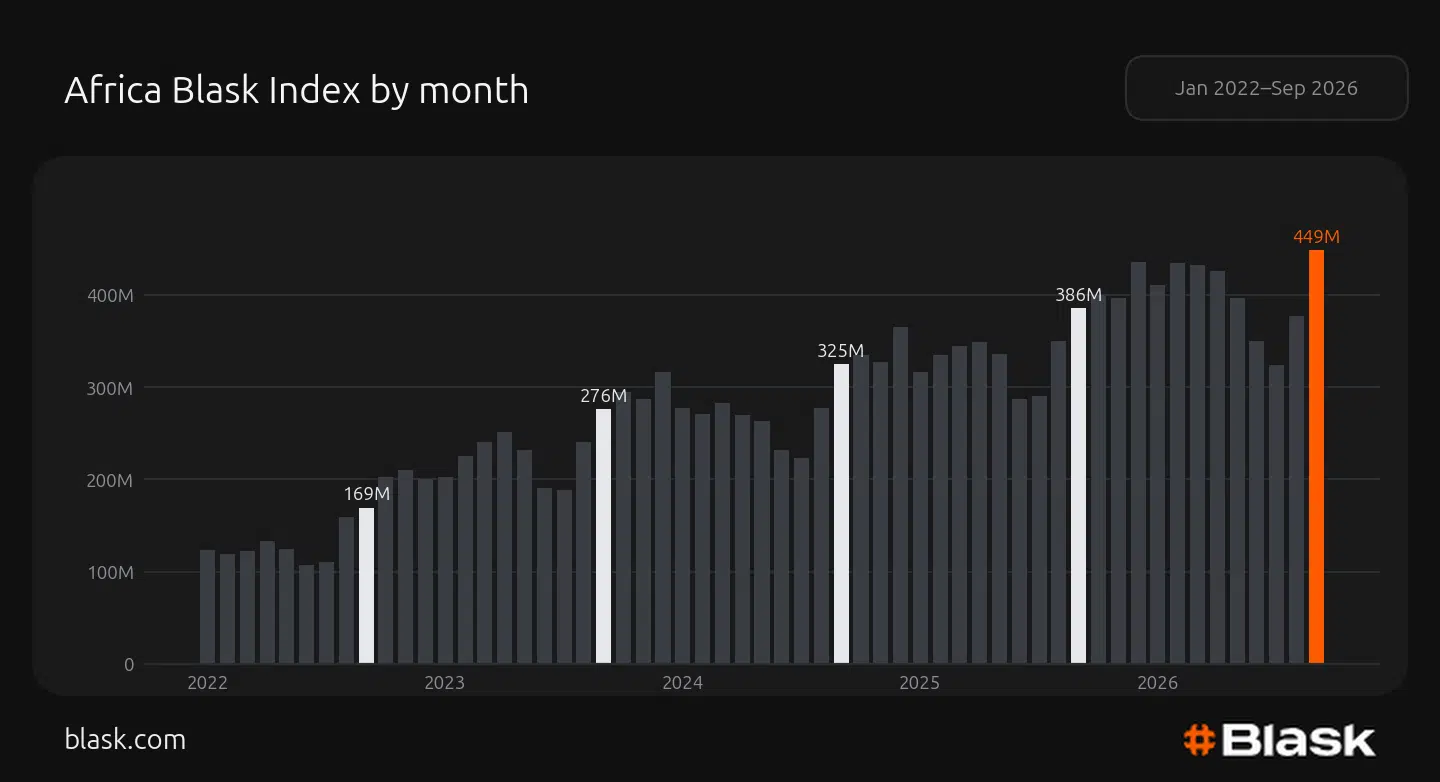
Four markets also established individual demand records — the Democratic Republic of the Congo, Zambia, Botswana and Zimbabwe.
Revenue benchmark reaches $765.6 million
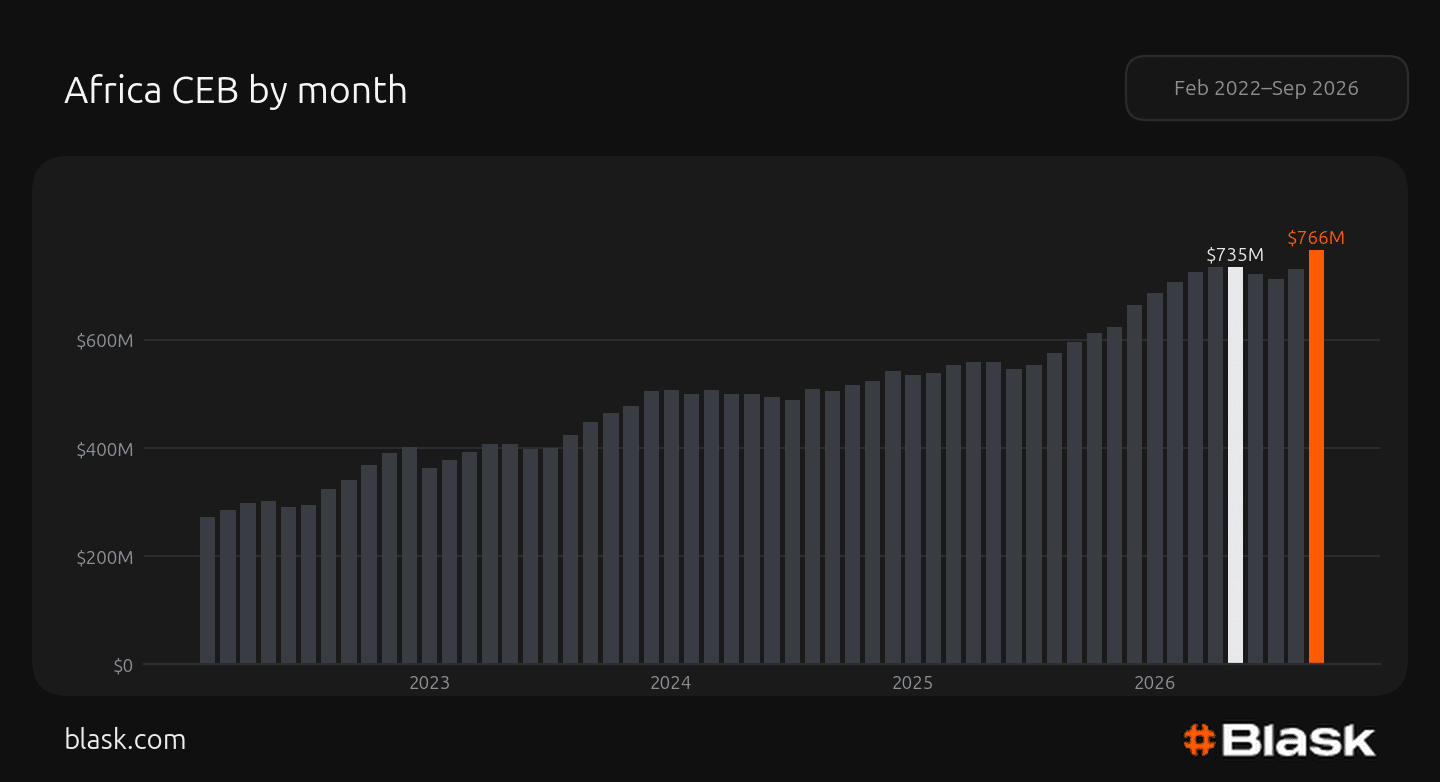
September brought a second regional record in CEB, Blask’s projected revenue metric. The monthly total reached $765.6 million, exceeding the previous high of $734.5 million in May.
The two measures capture different aspects of market activity. Blask Index tracks demand through normalized search data, while CEB provides a revenue benchmark rather than reported operator earnings.
Recovery gathers pace ahead of the year-end season
The September increase extended a recovery that began in August, following three consecutive monthly declines from May through July. August delivered 16% growth; September accelerated to 19%.
That acceleration departed from the pattern observed in every year from 2022 to 2025, when August’s monthly percentage gain exceeded September’s. This year’s August-to-September increase was also the strongest in the four-year comparison.
Historically, African demand has been concentrated toward year-end. September, October, November and December occupied the four highest monthly positions in each of the four complete years tracked by Blask.
The annual peak arrived in December in 2023, 2024 and 2025, standing 13–14% above September in each year. In 2022, demand topped out in November.
Blask: Alberta’s licensed brands hold 64% of demand but 36% of projected revenue
PlayAlberta retained almost the same provincial demand share after private operators entered the legal market. Much of its licensed competition already had an audience before opening day.
By September 2026, locally licensed brands accounted for 64% of Alberta’s iGaming search demand, according to Blask Index. Their share of CEB, Blask’s projected revenue metric, was considerably smaller at 36%.
The province opened its market to private operators on July 13, ending PlayAlberta’s position as the sole legal iGaming brand. Yet the expansion of licensed competition barely changed the incumbent’s share of provincial demand: 15.2% in September, compared with 15.6% in June.
Existing audiences move into the licensed category
Most demand attributed to the onshore market came from brands that Albertans were already searching for before regulation expanded.
Excluding PlayAlberta, the operators that subsequently obtained local licences — including Spin Casino and Betway — collectively represented 42% of provincial demand in June. That was almost three times PlayAlberta’s share at the time.
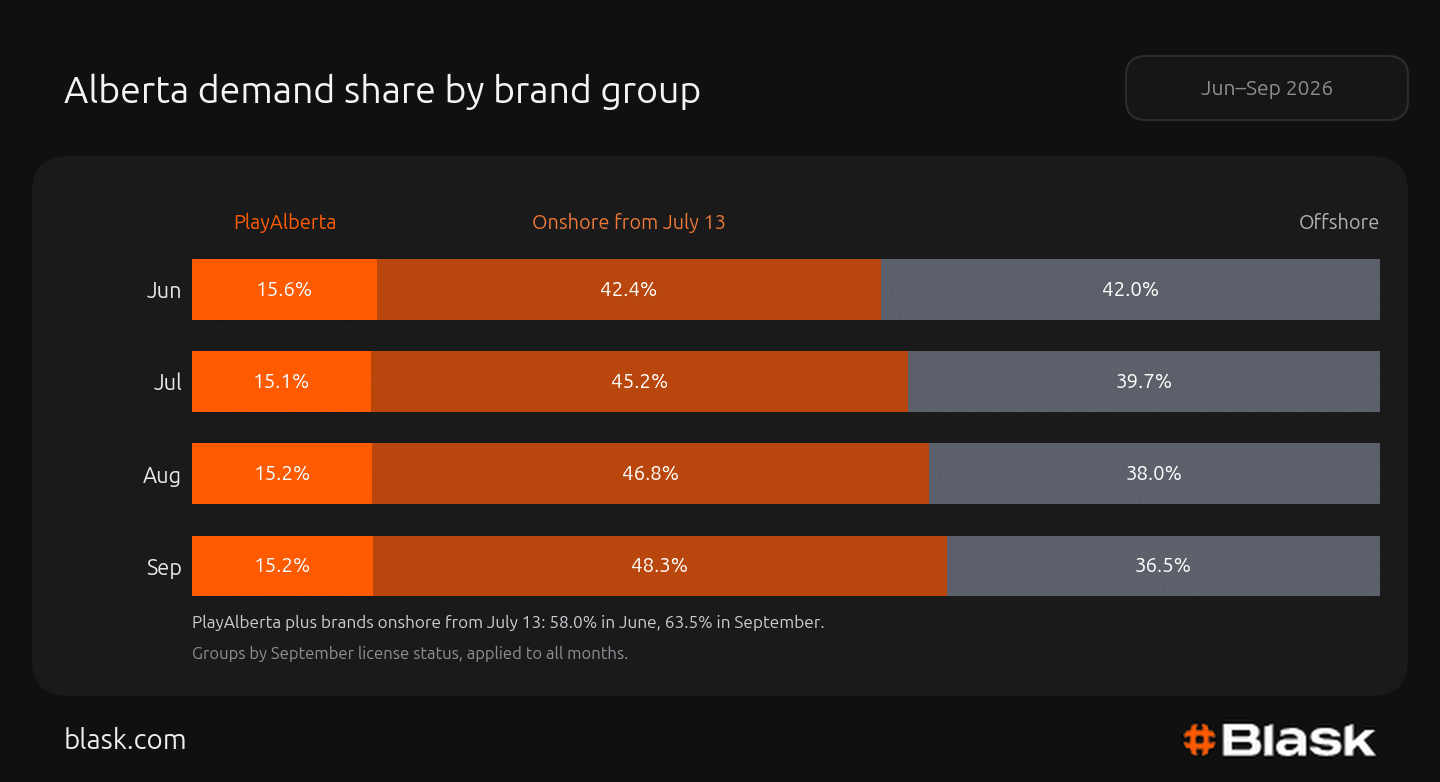
The licensed segment’s subsequent gain in share accompanied a decline in absolute demand. Between June and September, demand for the licensed group fell 11%, while operators that remained unlicensed recorded a steeper 30% contraction.
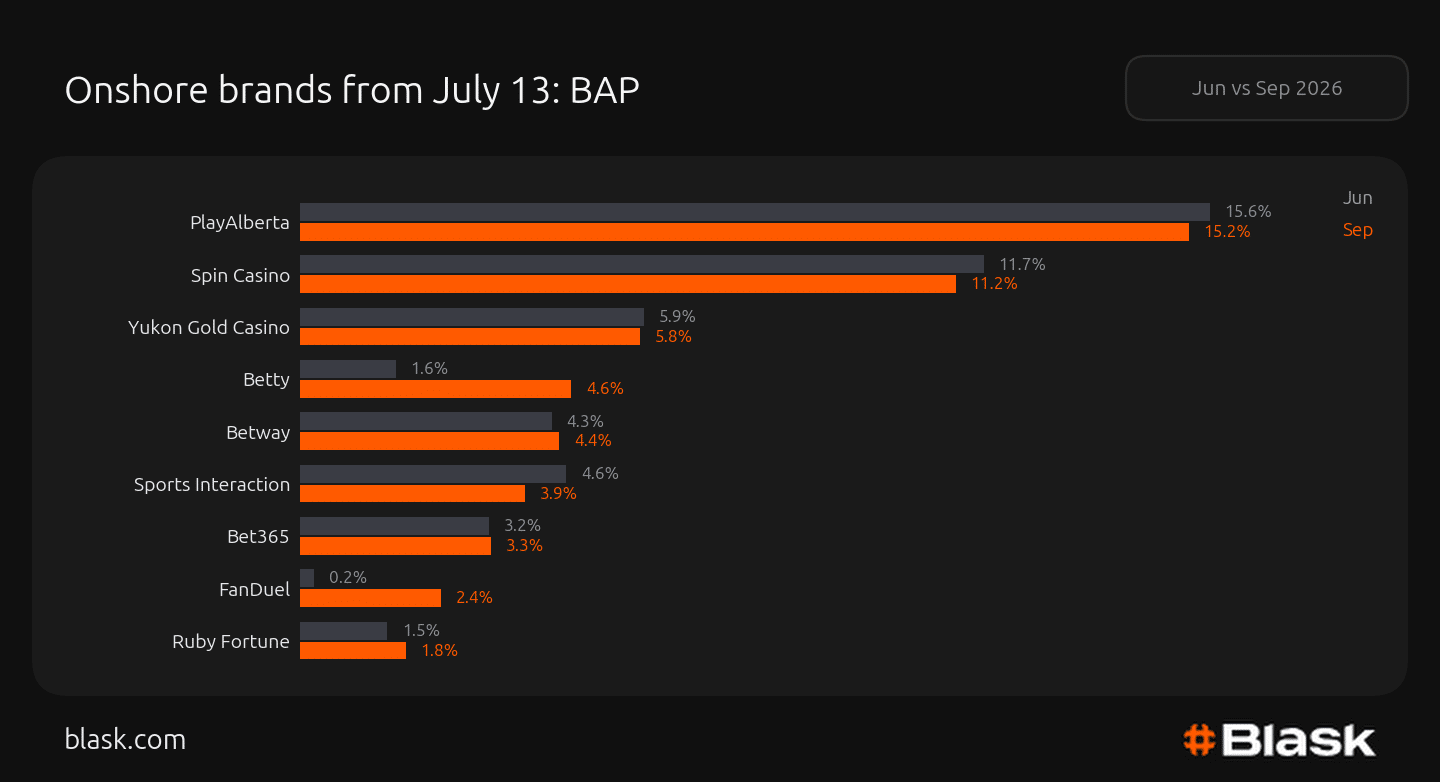
PlayAlberta remained the largest licensed brand, accounting for 24% of onshore demand, ahead of Spin Casino. Elsewhere among licensed operators, FanDuel and Betty together gained approximately five percentage points of demand share, while Sports Interaction lost 0.7 points.
Stake leads the September revenue benchmark
The gap between licensed demand share and licensed CEB share reflected the continuing weight of offshore brands in the revenue estimates.
Stake ranked first by September CEB at $32.2 million, more than twice PlayAlberta’s $14.1 million. It was still classified as offshore during that reporting period.
Stake received its Alberta licence on October 6, making October the next period to watch for a change in the distribution of CEB between licensed and offshore operators.
Blask: Pragmatic Play claims 6 places in Q3’s 10 most visible casino games
Gates of Olympus titles occupied three of the first four positions, while country rankings revealed a different set of favourites.
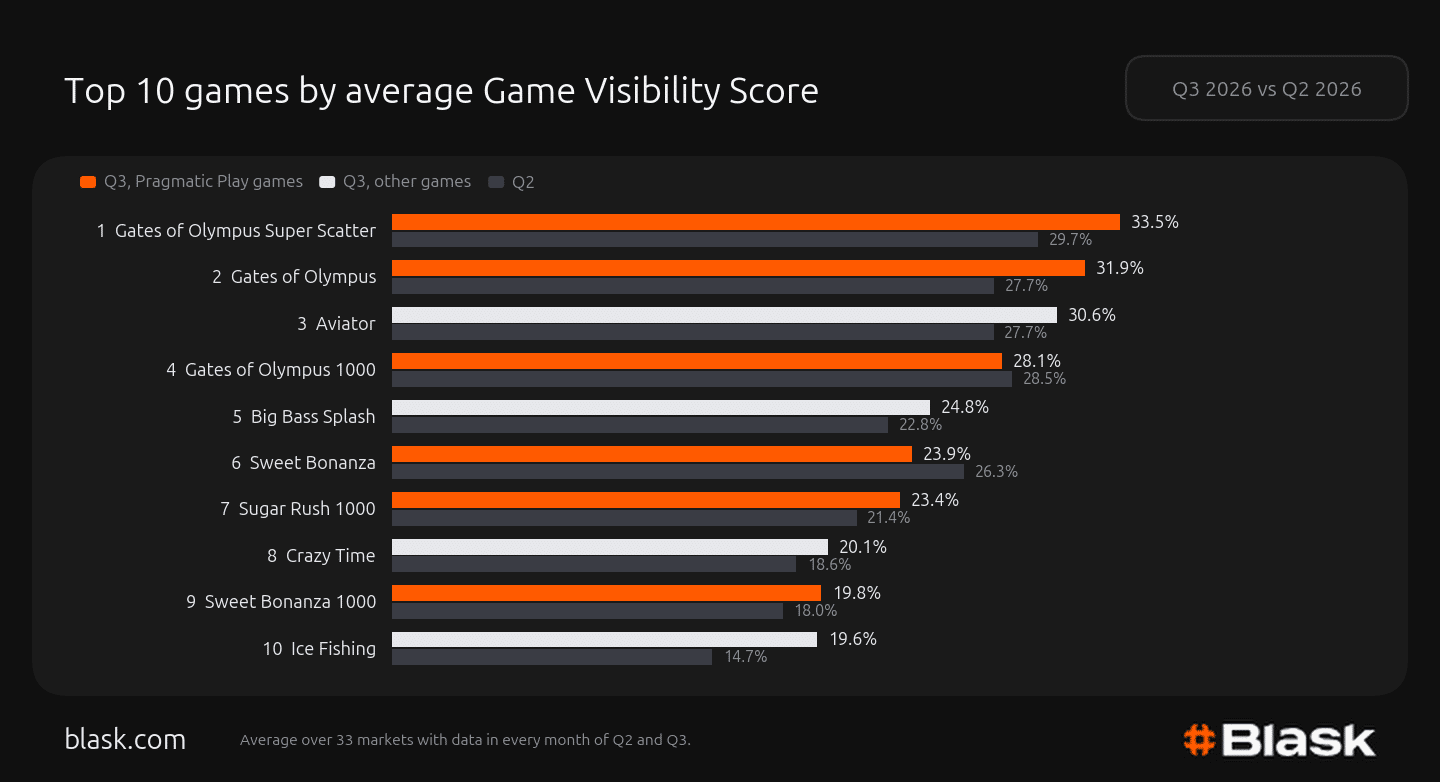
Pragmatic Play supplied six of the ten highest-ranked casino games by average Game Visibility Score in Q3 2026. Its Gates of Olympus series accounted for three of the top four, led by Gates of Olympus Super Scatter.
Super Scatter recorded an average score of 33.5%, improving by 3.8 percentage points from Q2. The original Gates of Olympus finished second, followed by Aviator. Gates of Olympus 1000 slipped from second place to fourth.
The comparison covers markets where Blask tracked games throughout all six months spanning the second and third quarters.
Evolution’s Ice Fishing achieved the largest score increase among the top ten, adding 4.8 percentage points. Sweet Bonanza moved furthest in the opposite direction, losing 2.4 points.
Country leaders extend beyond the global top ten
Aviator’s strongest positions included Ghana, Nigeria and South Africa, where it ranked first with scores ranging from 86% to 90%. In Brazil, it shared the lead with Fortune Tiger at 79%.
Big Bass Splash topped both Britain and Ireland with a score of 71%. Book of Ra games led in Germany, Austria and Italy; Book of Ra Deluxe specifically held first place in the latter two markets.
Several national leaders did not appear in the global top ten at all. Alongside Fortune Tiger and Book of Ra Deluxe, that group included Australia’s highest-ranked title, Coin Strike: Hold and Win.